You have spent years building your business. Then one day, the phone rings with an offer.
Suddenly, every financial decision you have made is on display.
The difference between a strong sale price and a discounted one is rarely just about how good your product or service is. Buyers are looking at the quality of your earnings, the reliability of your financial reporting, your customer concentration, your tax position, your ownership structure, and how easily they can verify the numbers.
If your financials are clean, credible, and easy to understand, buyers can focus on the value of the business.
If they are messy, inconsistent, or difficult to explain, buyers start pricing in risk.
Across Ontario, we have worked with business owners in industries including restaurants, construction, healthcare, professional corporations, e-commerce, real estate, and consulting. One lesson comes up repeatedly:
The work that protects your valuation starts months before the offer, not the week before closing.
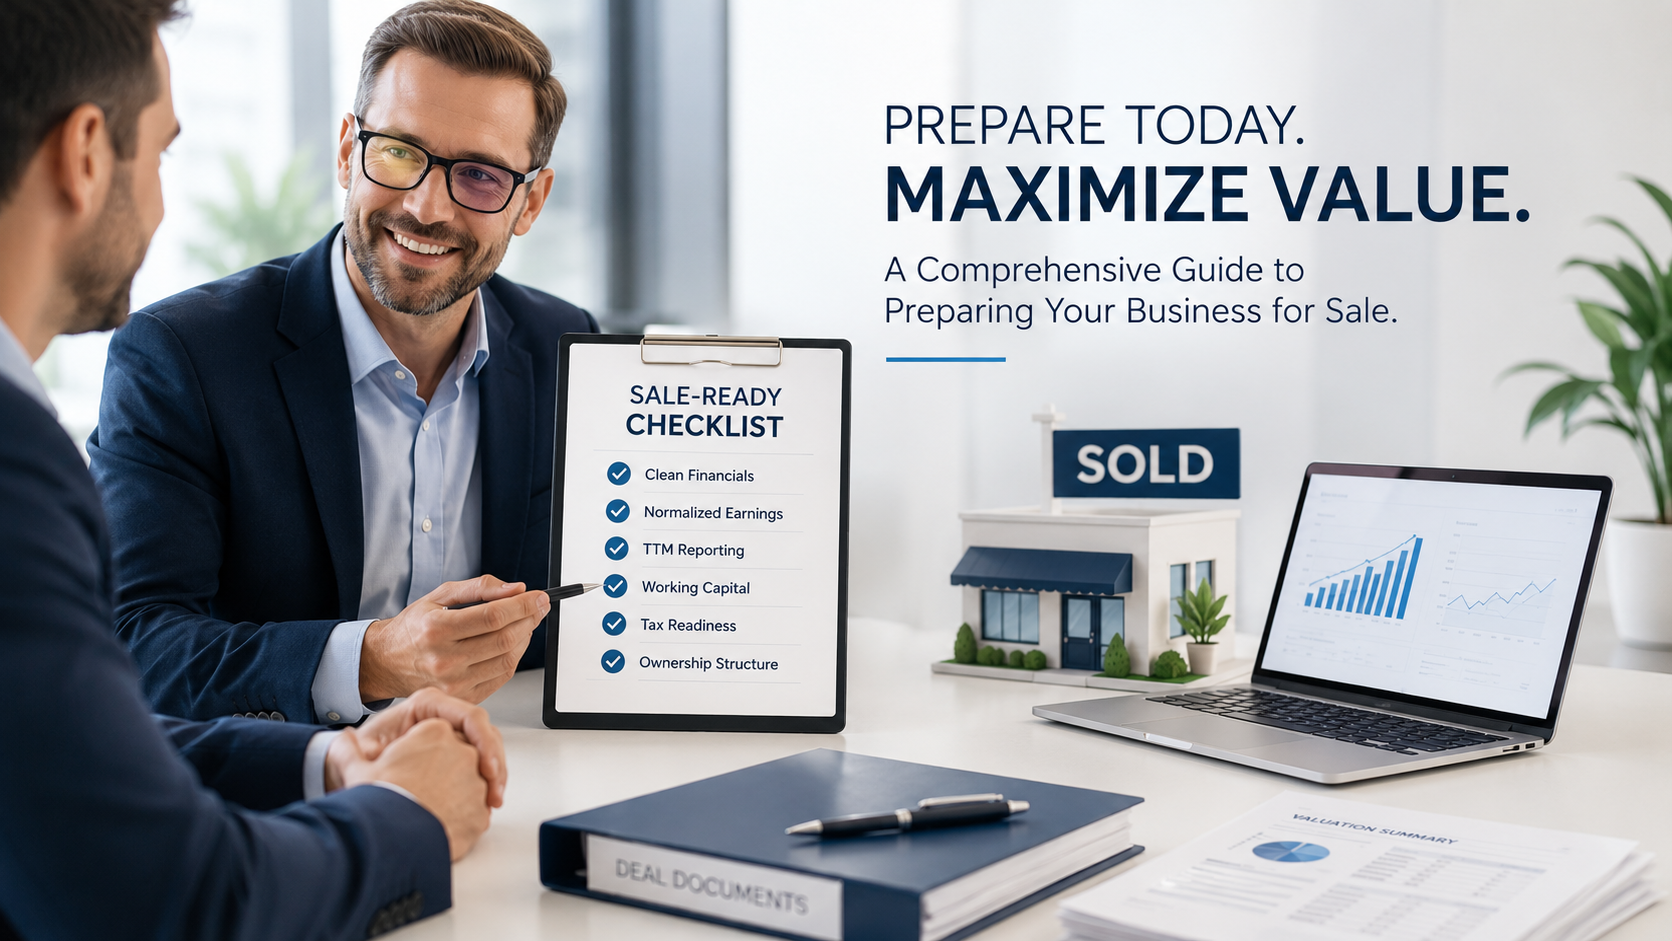
Here is the financial checklist every owner should consider before selling a business.
1. Get your books fully current and buyer-ready
The foundation of any business sale is clean financial reporting.
Buyers and their advisors will want to understand exactly how the business has performed over time. That means reviewing your income statement, balance sheet, cash flow, bank activity, payroll, HST, accounts receivable, accounts payable, inventory, shareholder accounts, and supporting documentation.
If the books are months behind, filled with unexplained transactions, mixed with personal expenses, or constantly changing, confidence drops quickly.
And when confidence drops, valuation often follows.
Before going to market, your books should be fully reconciled and current. Monthly reporting should be consistent, major balance sheet accounts should be supportable, and unusual transactions should already be explained.
A buyer should be able to review the last several years and see a business that is financially controlled and professionally managed.
That alone can change the tone of due diligence.
2. Make sure your revenue is real, repeatable, and correctly recognized
Revenue is not valuable simply because it appears on an income statement.
Buyers want to know how reliable that revenue is.
They will look at questions such as:
- Is the revenue recurring or transactional?
- Are contracts in place?
- Is revenue dependent on one or two major customers?
- Are there significant returns, credits, discounts, or cancellations?
- Is revenue being recognized consistently?
- Is growth sustainable?
- Is revenue tied heavily to the owner personally?
For contractors, revenue may need to be matched properly to project progress and milestones.
For subscription businesses, revenue may need to be recognized over the service period.
For professional service firms, the buyer may want to understand retainers, recurring engagements, client churn, and work in progress.
The cleaner and more defensible your revenue is, the easier it becomes for a buyer to trust your historical performance.
And trust has value.
3. Normalize your earnings before the buyer does
One of the most important numbers in a business sale is often not the accounting net income shown on your financial statements.
It is the sustainable earnings the buyer believes the business can generate under new ownership.
Depending on the size and type of business, buyers may focus on EBITDA, adjusted EBITDA, seller's discretionary earnings, or another measure of normalized cash flow.
This is where proper financial preparation can materially affect valuation.
Before a sale, we review items such as:
- Owner compensation
- Personal or discretionary expenses
- One-time legal or consulting costs
- Non-recurring repairs
- Unusual gains or losses
- Related-party transactions
- Below-market or above-market rent
- Family members on payroll
- One-time revenue
- Expenses that will disappear after closing
But there is an important distinction between a legitimate adjustment and wishful thinking.
A buyer will not simply accept a spreadsheet claiming that hundreds of thousands of dollars of expenses should be added back.
Every adjustment should be reasonable, supportable, and documented.
When normalized earnings are prepared properly, the owner enters negotiations knowing the earnings number the buyer is likely to value and having the evidence to defend it.
4. Understand the trends in your trailing twelve months
A buyer rarely values a business based only on what happened two years ago.
They want to know what is happening now.
That is why trailing twelve-month reporting, often called TTM or LTM reporting, is so important during a sale.
The buyer will look at trends such as:
- Revenue growth
- Gross margin
- Operating margin
- Customer retention
- Payroll costs
- Overhead
- Working capital
- Recurring revenue
- Customer concentration
- Recent profitability
If the business generated strong earnings last year but margins have declined during the most recent six months, the buyer will notice.
If revenue is seasonal or uneven, the owner should be able to explain why.
If one major customer represents 40% of sales, that concentration risk should be identified before the buyer raises it.
Good TTM reporting does more than present numbers.
It tells the financial story of the business.
5. Clean up your balance sheet
Many owners focus almost entirely on the income statement when preparing for a sale.
Buyers do not.
The balance sheet can reveal issues that materially affect a transaction.
Before a sale, review:
- Accounts receivable
- Old or uncollectible receivables
- Accounts payable
- Inventory
- Shareholder loans
- Intercompany balances
- Equipment and fixed assets
- Corporate debt
- Accrued liabilities
- HST balances
- Payroll liabilities
- Related-party balances
Old receivables that should have been written off, stale inventory, unexplained shareholder advances, or unreconciled tax balances create unnecessary questions during due diligence.
A clean balance sheet makes the business easier to understand and reduces the opportunity for the buyer to challenge the numbers.
6. Understand working capital before negotiating price
One of the most misunderstood areas in a business sale is working capital.
An owner may negotiate a purchase price and assume that is the number they will receive.
Then the working capital adjustment appears.
Many transactions require the business to be delivered with a normal level of working capital so the buyer can continue operating it immediately after closing.
That can include items such as receivables, inventory, prepaid expenses, and accounts payable.
If the required working capital level has not been analyzed before negotiations begin, the seller can be surprised by a significant closing adjustment.
The time to understand working capital is before signing a letter of intent, not after.
7. Get your ownership and corporate records in order
A buyer needs to know exactly what they are buying and who owns it.
Before a transaction, confirm that corporate and financial records agree.
That includes reviewing:
- Share ownership
- Share transfers
- Shareholder agreements
- Options or warrants
- Shareholder loans
- Related companies
- Holding companies
- Intercompany transactions
- Corporate minute books
- Ownership of major assets
- Ownership of intellectual property
A messy ownership structure can delay a transaction, create legal uncertainty, and sometimes lead to renegotiation.
A clean ownership structure tells the buyer that the business has been professionally managed.
8. Resolve tax and compliance issues before due diligence
Tax problems rarely improve after a buyer discovers them.
Before going to market, make sure corporate income tax filings, HST returns, payroll remittances, information returns, and other compliance obligations are current.
Outstanding CRA balances, unresolved audits, late filings, or unexplained tax positions can complicate a transaction and create holdbacks or indemnities.
For owner-managed corporations, shareholder transactions should also be reviewed carefully.
This is particularly important where significant amounts have moved between the owner and the corporation over the years.
A buyer wants clarity.
The seller should be able to provide it.
9. Think about tax structure before signing the deal
The purchase price matters.
The structure of the transaction can matter just as much.
A business sale may be structured as a sale of shares, a sale of assets, or some combination of the two.
The tax consequences can be very different.
For some Canadian business owners, a properly structured share sale may provide access to the Lifetime Capital Gains Exemption where the relevant requirements are satisfied.
That means pre-sale tax planning can be extremely valuable.
Depending on the circumstances, owners may need to consider issues such as:
- Share sale versus asset sale
- Qualified small business corporation requirements
- Corporate purification
- Holding companies
- Excess cash or investment assets
- Shareholder loans
- Capital dividend account balances
- Retained earnings
- Family ownership
- Estate or succession planning
These conversations should happen before the transaction structure is locked in.
Once a letter of intent has been signed, some planning opportunities may become more difficult.
10. Know the difference between purchase price and what you actually keep
A $3 million offer does not necessarily mean the seller receives $3 million.
The final amount that ends up in the owner's hands can be affected by:
- Corporate debt
- Working capital adjustments
- Transaction costs
- Legal fees
- Accounting fees
- Taxes
- Holdbacks
- Earn-outs
- Vendor financing
- Escrow
- Shareholder loans
- Closing adjustments
That is why every owner preparing for a sale should have a net proceeds analysis.
You should understand not only what the business may be worth, but also what you are likely to keep after the transaction is complete.
For many owners, that is the number that actually matters.
11. Reduce customer and owner concentration risk
A profitable business can still receive a lower valuation if too much of the business depends on one customer, one employee, or the owner personally.
Buyers look carefully at concentration.
If 50% of revenue comes from one customer, that is a risk.
If every important client relationship belongs personally to the owner, that is a risk.
If the business cannot operate for two weeks without the owner, that is a risk.
The more transferable and diversified the business becomes, the more attractive it generally becomes to a buyer.
This is why exit preparation is not only an accounting exercise.
It is also an operational exercise.
12. Prepare the financial story before the buyer creates one for you
Every business has unusual years.
Maybe you opened a second location.
Maybe you invested heavily in marketing.
Maybe a major customer left and was replaced six months later.
Maybe margins temporarily declined because of supply chain problems.
Maybe the owner intentionally reduced profitability by reinvesting aggressively in growth.
Those facts may be completely reasonable.
But if they are not explained clearly, the buyer will create their own explanation.
Good exit preparation means anticipating the questions before they are asked.
Your reporting should explain the business, not simply present numbers.
What proper exit preparation looks like
Ideally, an owner should begin preparing six to twelve months before going to market.
Sometimes the process should start even earlier.
We typically begin by reviewing:
- Historical financial statements
- Current bookkeeping
- Revenue quality
- Normalized earnings
- TTM performance
- Balance sheet accounts
- Working capital
- Customer concentration
- Corporate structure
- Tax compliance
- Potential tax planning
- Expected valuation
- Estimated net proceeds
Then we identify the issues that could reduce valuation or slow down due diligence.
Some can be fixed immediately.
Others may take several months.
The objective is simple:
Find the weaknesses before the buyer does.
Due diligence should confirm your value, not discover your problems
When the buyer's accountants, lawyers, and advisors open your books, there should be very few surprises.
The financial statements should reconcile.
The tax filings should be available.
Revenue should be supportable.
Add-backs should have documentation.
Working capital should already be understood.
Shareholder and related-party transactions should be explained.
The ownership structure should be clear.
Instead of spending the transaction defending the quality of your records, you can spend it defending the value of your business.
That is a much stronger negotiating position.
Selling your business is a process, not a moment
The sale of a business may be the largest financial transaction of an owner's life.
It deserves more preparation than simply waiting for an offer.
Clean financials, normalized earnings, credible TTM reporting, strong tax planning, clean ownership records, and a clear understanding of working capital can materially affect how a buyer views the business.
The objective is not to make the company look better than it is.
It is to make sure the value you have genuinely created is visible, credible, and defensible.
At MiAccounting, we help Ontario business owners prepare financially for business sales, acquisitions, valuations, and succession.
If you are thinking about selling your business in the next one to three years, that is not too early to start.
In fact, it may be exactly the right time.
The best exit planning happens before you need to exit.